

3.9x earnings
53% of the market cap is sitting in net cash.
0.78x of tangible book value
67% inside ownership
7.5% dividend yield
$320 million of contracted revenue already on the books.
23% ROIC
“A brilliant man who can’t get any money from other people and is working with a very small sum probably should work in very obscure stocks, searching out unusual mispriced opportunities.” - Charlie Munger (2001 Berkshire Hathaway annual meeting)
I think Charlie put it well. Obscure stocks equals fewer eyeballs which means less efficient pricing. This is why young Buffett went through tens of thousands of pages in the Moody’s manuals in the 1950’s finding tiny companies trading below liquidation value. Or why Li Lu worked though the Korean company handbook in the early 2000s, and why in his early career Joel Greenblatt built his edge in small caps which outperformed the market significantly.
Finding miss pricing is the whole game and a lot of these miss pricings can be found in obscurity. And it’s hard to get more obscure than a sub $100 million market cap Hong Kong company.
Let’s dive in.
Baguio Green Group (HKEX: 1397)
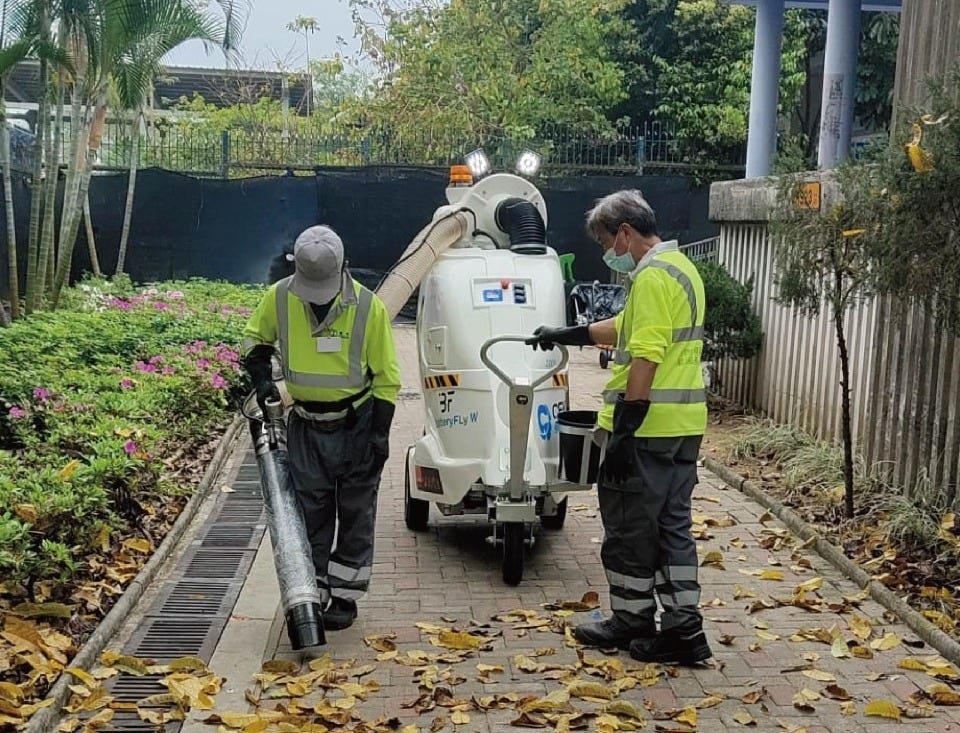
Founded in 1980 Baguio is Hong Kong’s largest cleaning, waste management, landscaping and pest control contractor. They operate a fleet of trucks, recycling stations, landscaping crews, pest technicians and roughly 8,000 employees whose job is keeping hospitals, universities, airports and the Hong Kong streets clean.
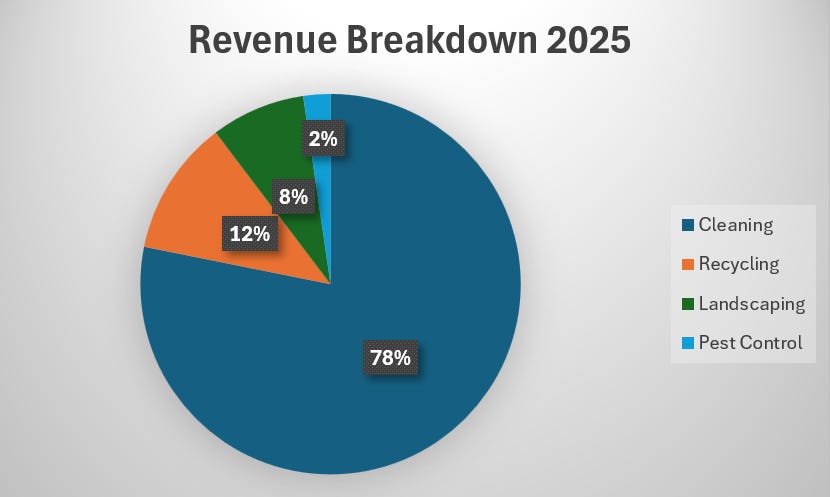
Baguio clients are the Hong Kong Housing Authority, the Hospital Authority, the Jockey Club, Hong Kong International Airport, and 33 government sports venues. Regarding the revenue breakdown the chart is below.
Also there is a new marine cleanup contract. Worth $6.4mn a year, the company’s first. I guess the old dog can learn new tricks. The elephant in the room is they mainly rely on 1 customer which is the Hong Kong government. They have been 44%-55% of revenue since 2022. However, concentration of revenue has fallen 2 years straight. 55% down to 44%.
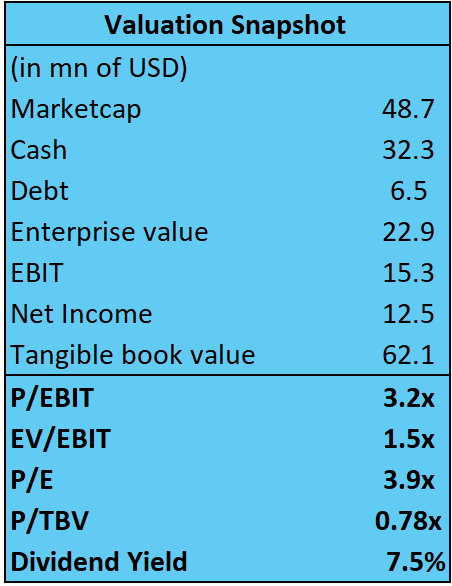
Baguio already has $325mn of contracts on their books. With $200 million of that being recognised in 2026. Although it has very thin margins and from that $200 million of sales they’ll make about $8mn net income. At a $48.7mn market cap that’s a day 1 return of 16.4% keep in mind they have net cash of 25.8mn. You could argue it’s difficult to forecast if they are going to win future contacts however they have been in business for 46 years.
Although I used last year’s numbers for the valuation snapshot, it’s better to use normalised earnings. Average net income across the last three years instead and you get $8.5 mn a year. And last EBIT comes to $11.6mn On that normalized basis, EV/EBIT is closer to 2.0x and P/E is 5.7x. Still cheap.
Regarding return on capital using Joel Greenblatt formula of EBIT / (Net working capital + Fixed assets) we get the last 3 year average ROIC of 23% pretty good.
But there’s no moat. Cleaning segment margins bounce between 6% and 12% with no clear direction, because Baguio wins its revenue by bidding against competitors at whatever price clears the tender. The annual report says ,“cleaning revenue fell 9% last year “due to intense competition within the cleaning industry.”
The one bright spot is recycling, margins climbed steadily from 0.4% to 15% over four years, riding Hong Kong’s push toward Zero Landfill by 2035. Real tailwind. Still only 11.5% of revenue though, so don’t get ahead of yourself.
Management
Chairman Ng Wing Hong and family own 67%. David Webb, a well known Hong Kong governance watchdog / investor, owns almost 6%. I have no idea what happens to his holding since his passing in January of this year (Rest in peace).
Capital allocation is decent, not exceptional. Dividend’s conservative and covered, 30% payout, 7.5% yield. The 2022 capex surge tracked real 41% revenue growth. They had a massive 2025 headcount cut. What they haven’t done is anything really active with the cash pile. But I think no capital allocation is better than bad capital allocation.
One flag is that the Chairman’s private IT company sells services back to Baguio, capped at $770,000 a year, audited annually. Small, but worth naming. Futhermore Baguio is audited by KPMG.
Final Thoughts and checklist
You are paying 5.7x normalised earnings for a 46 year old company that generates 23% ROIC. With net cash covering 52% of the market cap with management that has real skin in the game. All this while they pay out a 7.5% dividend and a steep discount to tangible book value. The downside is protected by the massive net cash position and the discount to tangible book.
When looking at a stock I run it though my back of the envelope checklist which is the following.
Is it cheap?: Yes. 3.9x trailing earnings, 5.7x on normalized earnings, and net cash covers 53% of the market cap. Yes, cheap on every real measure.
Is the business good?: Decent. ROIC is 23% but there’s no moat and revenue has to get won. Decent business.
Is management trustworthy and competent ?: Yes. Insiders own 67%, audited by KPMG, dividend’s conservative and covered. Trustworthy, yes, but passive, they haven’t done anything that active with the growing cash pile. No capital allocation is better than bad capital allocation.
What else am I missing ?: One customer, the Hong Kong government, has been 44%-55% of the revenue since 2022 although the trend is improving.
Why does the opportunity exist?: It’s a sub $50mn market cap Hong Kong micro cap with zero analyst coverage.
Disclaimer: The information provided in this article is for educational and informational purposes only. It does not constitute financial advice, investment recommendations, or an offer to buy or sell any securities. You should conduct your own research and consult with a qualified financial advisor before making any investment decisions. The author may hold positions in the companies mentioned, but the opinions expressed are their own and are subject to change without notice. Investing involves risk, and past performance is not indicative of future results.